Should you take the offer for your excess stock?
Usually, if it's fair. Excess stock rarely gets more valuable while it waits, and holding costs keep running, so a fair first offer is often the best you'll see. Judge it on the net cash after costs, whether it covers the whole parcel, the payment terms, and whether the buyer will respect where your stock ends up.
Owners often spend weeks deciding whether to take an offer on their excess stock. John Coorey's answer, after more than 30 years of buying it, is short:
"If the first offer is fair, take it. I've very rarely seen excess stock get more valuable sitting in a warehouse. The second offer is usually lower."
That's not a sales line. It's what happens when stock ages. But "fair" is doing a lot of work in that sentence, so here is how to tell whether an offer is one you should accept.
Why does excess stock usually lose value while you wait?
Because the reasons it became excess don't go away, and the costs of holding it keep adding up.
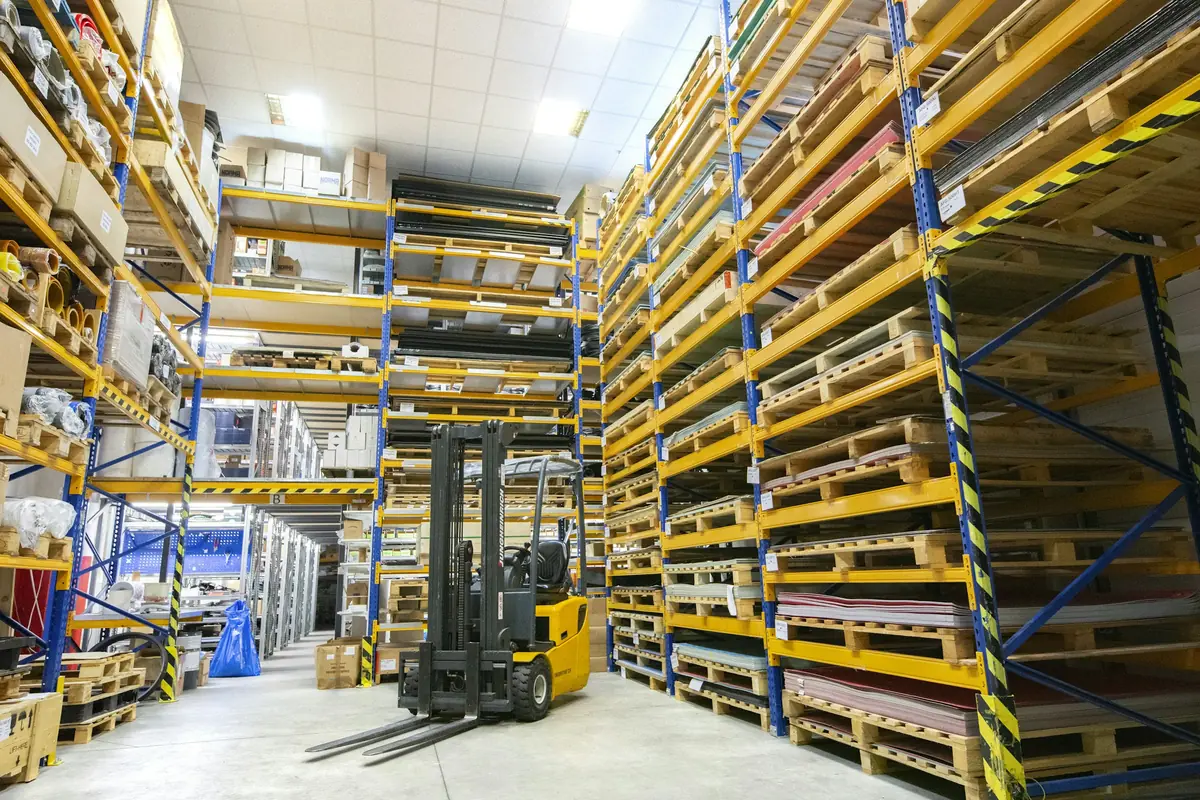
Stock becomes surplus for ordinary reasons: a cancelled order, over-ordering, a change in fashion or packaging, a line the retailer dropped, over-manufacture. The stock itself is usually fine. But every month it sits:
- the season or trend moves further on
- best-before or use-by dates get closer
- newer models or packaging replace it
- warehouse rent, insurance and finance keep running
- buyers see more competing parcels, and their budgets get spent elsewhere
A department-store purchasing manager receives 200 to 300 emails a day. Your parcel is competing for their attention with everyone else's. It doesn't get easier with time.
How do I judge an offer for my excess stock?
Compare the net cash you'd actually get, and when, against your realistic alternatives, not against what you paid.
Work through these:
1. What's the net figure?
Start with the offer, then subtract anything you'd still have to pay: freight, handling, palletising, removing labels, storage until collection. A higher offer that leaves you paying the freight can be worth less than a lower one that doesn't.
2. What does holding it cost?
Add up a month of storage, insurance and finance on the stock, and estimate how much value it loses each month (dates, seasons, models). Compare that to the gap between this offer and the price you're hoping for. If the gap closes in a few months, waiting is a gamble with poor odds.
3. Is it for the whole parcel, or just the best lines?
This one matters more than most people expect. A buyer who cherry-picks the fast sellers leaves you with the slow ones, which are now harder to sell because they're on their own. A whole-parcel offer may look lower per unit but clears everything.
| Whole-parcel offer | Cherry-picked offer | |
|---|---|---|
| Price per unit | Lower average | Higher on the lines taken |
| What's left | Nothing | The slow lines |
| Your next step | Done | Find another buyer for the leftovers, usually at a worse price |
| Total effort | One deal | Several |
4. What are the payment terms?
Who pays, how, and when? Is there a deposit? Does the stock leave before or after payment? Get it in writing. We guarantee: "We send payment promptly, as per our agreed terms."
5. Where will the stock end up?
If it's your brand, or you sell to retailers, this can matter more than the price. Ask the buyer which channels and markets they'll sell into and whether they'll agree to your restrictions. A good stock buyer will. Our first guarantee is: "We strictly follow your guidelines in relation to pricing and distribution locations." More in protecting your brand when clearing stock.
6. Can they actually take it?
Collection, timing, paperwork. A great price from a buyer who can't arrange collection for months isn't a great price.
Speed vs price: which matters more?
For most excess stock, speed matters more than people think, because the price you're holding out for is often falling.
There are exceptions. If the stock is long-life, compact, cheap to store and in demand, you can afford to wait for a better buyer. If it's short-dated, seasonal, bulky or taking up space you need, a fair offer now is usually worth more than a hoped-for offer later.
A useful test: write down the price you'd need to wait for. Then ask who, specifically, will pay it and when. If you can't name them, take the offer.
A worked example of comparing two offers
Say you have a parcel of mixed homewares taking up part of your warehouse. You have two offers.
- Offer A is for the whole parcel. The buyer arranges collection and pays on the terms agreed.
- Offer B is higher per unit but only for the three best-selling lines, about half the parcel. You pay freight to the buyer.
To compare them fairly:
- Take Offer B's total and subtract the freight.
- Estimate what you'd realistically get for the remaining half, and when. Be honest: these are the lines nobody wanted.
- Subtract the cost of storing that remainder until it sells, plus your time finding another buyer.
- Compare the result with Offer A.
More often than not, Offer A comes out ahead once the leftovers are counted properly, and it's finished. Sometimes Offer B wins, usually when the remainder is small or easy to sell. The point is to do the sum on the whole parcel, not just the attractive half.
What about holding out for the original price?
Expecting full market or cost price for excess stock is unrealistic. It became excess because the normal market didn't take it at that price.
That isn't a criticism of the product. Most excess stock is perfectly good. It's just in the wrong place at the wrong time: too much of it, the wrong season, a retailer who changed their range. A stock buyer earns a margin by finding the right place and time, and takes on the risk, freight and handling to do it. The offer reflects that.
Once you accept that the original price is gone, the decision gets simpler. The only questions left are who you sell to, on what terms, and how quickly.
How to avoid ending up here again
Not every overstock can be prevented, but a few habits help:
- Review slow movers regularly. A monthly look at stock that hasn't sold catches problems while there's still time and value.
- Set a clearance trigger. Decide in advance, for example, that anything unsold after a set period gets offered out.
- Order to realistic forecasts. Large minimum order quantities and volume discounts are tempting, but the discount disappears if half the order sits unsold.
- Agree flexible terms with suppliers where you can, such as smaller runs or the option to return unsold stock.
If you'd like help with importing, distribution or exporting more broadly, John also offers paid business consulting, separate from buying stock.
How to negotiate with stock buyers
Negotiate on the things that change your net result, not just the headline figure.
- Give a complete stock list. SKU, description, quantity, best-before dates, and cost or RRP if you're happy to share. Good information gets a firmer offer.
- Be honest about problems. Damaged cartons, short dates or labelling issues will be found. Disclosing them early stops the price changing later.
- Offer the whole parcel. Buyers pay more attention, and often pay more overall, when they can clear everything in one go.
- Trade on terms, not just price. Who pays freight, collection timing, payment timing and channel restrictions are all worth something.
- Ask how they valued it. A genuine buyer will explain the market they're selling into.
- Don't broadcast it. Sending the parcel to every buyer you can find tells the market it's struggling.
When should you not take the offer?
Walk away if the buyer won't put terms in writing, won't say how they'll pay, won't agree to reasonable restrictions on where your stock goes, or wants only the best lines at a price that leaves you worse off overall. Also hold off if the offer is clearly below what a realistic alternative would net you after costs, and you have the time and space to pursue that alternative.
If you're not sure what the stock is worth to begin with, read how much is my stock worth. If you're weighing eBay or auctions instead, see selling excess stock online vs to a buyer.
If you do walk away, set a date to review it again. An offer you turned down is useful information about what the market will pay, and it can help you decide what to do next.
How we make an offer
We buy the parcel ourselves and resell it through our own buyers: major retailers, discount chains, overseas buyers, charities, wholesalers and distributors. You don't pay us a fee.
- You send the details: stock list spreadsheet, photos, quantities, dates and location.
- John surveys the market discreetly to find out what the stock is worth.
- In most cases, he makes an offer to buy all of it. If buying the whole parcel isn't possible, he gives his best advice on how to sell it.
Collection is flexible and agreed per parcel, and there's no minimum size. We buy from anywhere in Australia, New Zealand and overseas.
Our four guarantees:
- "We strictly follow your guidelines in relation to pricing and distribution locations."
- "We send payment promptly, as per our agreed terms."
- "We place a priority focus on clearing your stock."
- "We speedily and discreetly convert your stock into cash at the highest possible price, without damaging your market position."
For more background, see our guide to overstocks or how we buy excess stock. Call John on 0411 430 047, email john@coorey.com, or send us your stock list.
Want an offer to compare?
Share the details of your stock, attach a stock list or photos if you have them, and we’ll get back to you personally.
Thank you!
If the matter is urgent please contact John Coorey directly through john@coorey.com or 0411430047.